


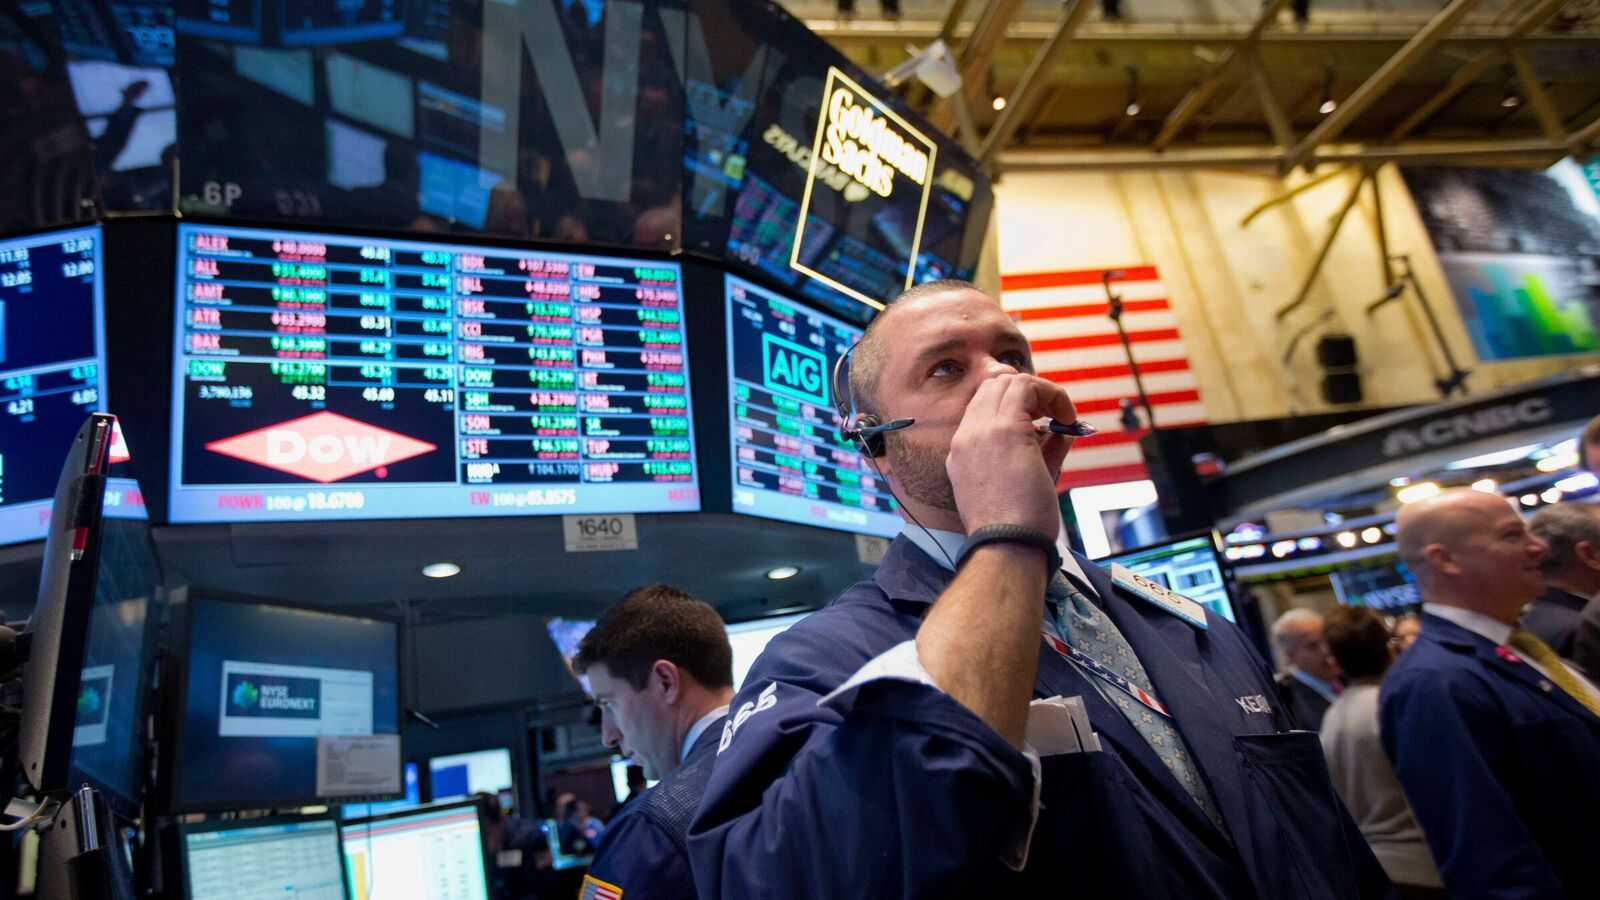
U.S. equity futures traded mixed early Wednesday, October 28, 2026, as investors braced for a crucial monetary policy announcement from the Federal Reserve alongside upcoming quarterly earnings from mega-cap technology giants Alphabet and Microsoft, CNBC reported. Market participants weighed ongoing macroeconomic policy against volatility in artificial intelligence financing and supply chains, while separate supply pressures mounted as global crude oil prices climbed following reports of Middle East supply disruptions.
According to data from TradingView, S&P 500 futures edged up 0.05% and Nasdaq-100 futures rose 0.3%, while Dow Jones Industrial Average futures slipped 0.2%. The mixed premarket session followed a positive regular trading day on Tuesday, October 27, when major U.S. benchmarks closed higher, led by semiconductor stocks and corporate financing announcements.
Federal Reserve Policy Expectations and Market Reaction
The Federal Reserve is scheduled to announce its latest monetary policy decision on Wednesday afternoon, wrapping up a two-day meeting. Market consensus widely anticipates that the central bank will keep benchmark interest rates steady within the target range of 3.75% to 4%, following a quarter-percentage-point rate cut at its September meeting. CME Group’s FedWatch tool indicated a roughly 92% probability that policymakers would maintain current rates, though analysts noted that market attention will focus heavily on any forward guidance from Fed Chairman Kevin Warsh regarding future policy adjustments.
Despite the prevailing expectation of a rate pause, macroeconomic pressures remain complex. Global crude oil prices moved sharply higher on Wednesday following reports that Houthi forces had targeted Saudi Arabia’s Ras Tanura refinery with a ballistic missile. Brent crude futures jumped 1.98% to $116.13 a barrel, while U.S. West Texas Intermediate futures gained 2.21% to $102.11 a barrel, heightening energy market volatility just as the central bank evaluates inflationary risks.
Semiconductor Strength and AI Financing
Chip stocks provided significant support to premarket and recent trading sessions, buoyed by major earnings and funding reports. South Korean chipmaker SK Hynix saw its Seoul-listed shares surge more than 8% after reporting record quarterly profits and announcing over $23 billion in shareholder returns through dividends and buybacks. The company reported that its DRAM and high-bandwidth memory chips are sold out through 2029, with industry shortages expected to persist until 2030. U.S. semiconductor equities followed suit, with Micron Technology rising 3.48%, ARM Holdings advancing 1.84%, and Advanced Micro Devices adding 1.17% in early Wednesday trade.
The broader artificial intelligence trade also drew momentum from Tuesday’s regular session, when Broadcom shares rose 4% after disclosing that a group of banks would provide $63 billion in financing to acquire chips and networking solutions for lease to Anthropic. Additionally, Alphabet shares gained 1.2% in premarket trading following reports that OpenAI was considering the purchase of Google tensor processing units, though financial terms were not disclosed.
Big Tech Earnings and Broader Market Sentiment
Wednesday’s post-market hours mark the official kickoff for Magnificent Seven earnings, with Alphabet and Microsoft reporting quarterly results. Microsoft shares edged down 0.2% in premarket trading as investors awaited fiscal first-quarter figures and monitored reports concerning potential corporate restructuring, including a voluntary buyout program under discussion. Meanwhile, Morgan Stanley chief U.S. equity strategist Mike Wilson told CNBC that the recent multi-month correction in technology equities may be nearing completion as markets efficiently digest valuation adjustments.
International markets reflected the cautious sentiment. The pan-European Stoxx 600 shed 0.27%, with the U.K. FTSE 100 down 0.33% and Germany’s DAX losing 0.11%. In Asia, Japan’s Nikkei 225 closed 1.08% higher, South Korea’s Kospi surged 6.63% on the back of semiconductor strength, and mainland China’s CSI 300 added 0.85%.